When Winners Stop Winning: Recognizing the Slow Deterioration of a Once-Great Position
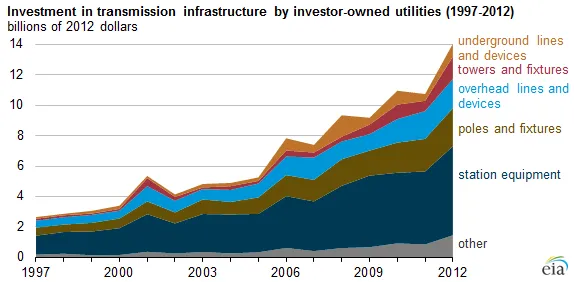
Photo: U.S. Energy Information Administration, Public domain, via Wikimedia Commons
There is a particular kind of portfolio damage that does not announce itself. It does not arrive with a dramatic earnings miss or a regulatory shock. It accumulates slowly, across quarters, sometimes across years — the gradual erosion of a position that was once your highest-conviction holding and has since become something you no longer examine closely because examining it closely would require a decision you are not ready to make.
This is portfolio decay. And it is responsible for more destroyed wealth among retail and professional investors alike than any single bad trade.
The Anatomy of a Decaying Winner
Understanding how a strong position deteriorates requires separating the mechanics from the psychology — though the two are deeply entangled.
On the technical and fundamental side, position decay typically follows a recognizable sequence. A company that earned its premium valuation through superior growth rates begins to see those rates moderate. This is often natural — large bases make percentage growth harder to sustain. But the market's tolerance for valuation compression depends entirely on whether decelerating growth is accompanied by expanding margins, improving free cash flow, or a credible reinvestment thesis. When deceleration arrives without those offsets, the multiple begins to contract even as earnings may still be growing in absolute terms.
Competitive dynamics are frequently the first signal that something structural has changed. The entry of a well-capitalized competitor, a technology shift that disadvantages the incumbent, or a regulatory development that compresses pricing power — these forces rarely destroy a business overnight. They pressure it incrementally, showing up first in gross margin trends, then in customer acquisition costs, and eventually in revenue growth itself. By the time the deterioration is visible in a headline earnings number, the stock has often already repriced significantly.
The Psychology of the Held Position
What makes portfolio decay so destructive is not the fundamental deterioration itself — it is the investor's response to early evidence of that deterioration.
When a position has been a winner, it carries a psychological weight that goes beyond its financial value. It is connected to the original thesis, to the research that supported it, to the identity of being right about something. Selling that position — particularly if it still reflects a gain from the original purchase price — requires admitting that the thesis has changed, which can feel uncomfortably close to admitting that the original judgment was flawed.
This is the mechanism behind what behavioral economists describe as the endowment effect: we place disproportionate value on things we already own, relative to the objective assessment we would apply to something we did not yet hold. Applied to a long-held equity position, the endowment effect manifests as a persistent reluctance to reassess on equal terms. The question is no longer "would I buy this today at this price?" — which is the only question that matters — but rather "I've held this for three years, how can I sell now?"
The result is a portfolio that accumulates positions held for reasons that no longer exist, while capital that could be redeployed into higher-conviction opportunities sits idle.
Patience Versus Self-Delusion: A Practical Framework
The most important distinction an investor can make is between a position experiencing temporary headwinds and one undergoing structural deterioration. Patience is a genuine edge in markets that systematically undervalue long-duration cash flows. But patience applied to a structurally impaired business is not a virtue — it is a euphemism for inaction.
A working framework for making this distinction involves three questions.
First: Has the original thesis been invalidated, or merely delayed? If you purchased a company because you believed it would take share in a growing market, and that market is now growing more slowly than anticipated, that is a thesis modification, not a thesis failure. If the market has structurally shifted away from the company's core offering, that is a different situation entirely.
Second: Are insiders and institutional holders behaving consistently with the original thesis? Sustained institutional outflows, combined with insider selling that departs from historical patterns, are worth treating as evidence — not proof, but evidence — that sophisticated holders are updating their own assessments. Form 13-F filings and Form 4 disclosures, both publicly available through EDGAR, provide this visibility.
Third: What would you need to see to change your mind? This is perhaps the most diagnostic question of the three. If you cannot articulate a specific, observable condition that would prompt you to exit the position, you are not holding with conviction — you are holding by default. Conviction has a falsifiable structure. It can be proven wrong by identifiable evidence. Stubbornness has no such structure. It simply waits.
The Exit Is Part of the Trade
Professional portfolio managers who consistently outperform do not necessarily make better entry decisions than their peers. What separates them, in many cases, is a more disciplined approach to exit. They treat the decision to redeploy capital with the same analytical rigor applied to the original investment — reviewing the current fundamental picture as if encountering the company for the first time, without the distortion of sunk cost or prior conviction.
Retail investors can adopt the same discipline by instituting a formal position review process — not a daily price check, but a quarterly reassessment of the underlying thesis against current evidence. Has the competitive position strengthened or weakened? Has management's capital allocation track record improved or deteriorated? Does the current valuation reflect an opportunity or a warning?
The exit, in other words, is not the failure of the trade. Holding past the point where the evidence supports holding — that is the failure.
Capital Has No Memory
One of the most liberating reframes available to investors is the recognition that capital, once redeployed, has no awareness of where it came from. The money you free up by exiting a deteriorating position does not carry the history of that position into its next deployment. It is simply capital, available to be allocated to the highest-conviction opportunity currently available.
Portfolio decay is, at its core, a failure of that reallocation discipline. It is what happens when past decisions crowd out present judgment. The antidote is not cynicism about prior convictions — it is the intellectual honesty to distinguish between a thesis that has proven durable and one that has simply proven comfortable.