Paid From the Balance Sheet: Reading a Dividend as a Signal, Not a Reward
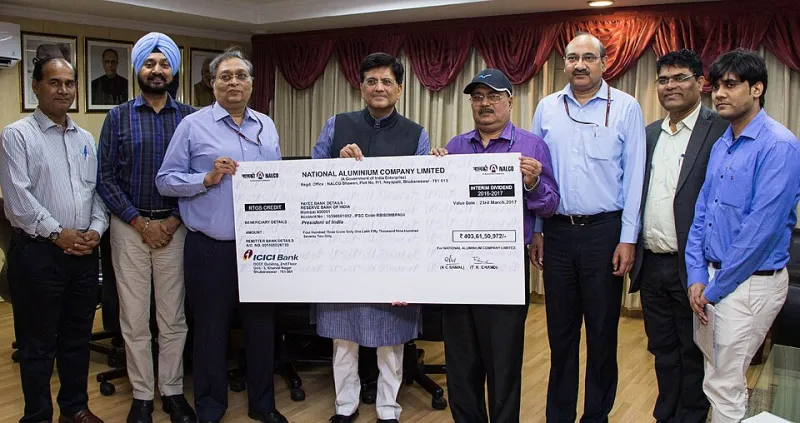
Photo: Ministry of Power, GODL-India, via Wikimedia Commons
A dividend is one of the few things in markets that arrives as a fact rather than an opinion. The cash lands. The statement confirms it. For investors told for decades that total return is the only honest scoreboard, the quarterly distribution still carries a weight a rising share price never quite matches. It feels like the company paying you for your patience.
That feeling is where the trouble starts. A payout is a financing decision before it is a reward, and the board declaring it is weighing cash needs, debt covenants, and investor expectations alongside your loyalty. When the distribution begins to outrun the business behind it, the loudest early warning is usually the yield itself.
The arithmetic that separates earned from borrowed
Start with the simplest test: is the dividend covered by cash the business actually generates? Earnings are an accounting construct. Free cash flow — operating cash flow less capital expenditures — is the money that could have been distributed without altering the capital structure. A payout ratio built on net income can look comfortable at 60% while the cash flow statement tells a different story, because depreciation, working capital swings, and capitalized costs all sit between the two numbers.
Compute the cash payout ratio directly: dividends paid divided by free cash flow. Below roughly 60% for a mature industrial or consumer business leaves room to absorb a bad year. Above 80%, the margin for error is thin. Above 100%, the company is drawing on its balance sheet, selling assets, or borrowing — and two of those three are temporary by definition.
Sector matters. REITs, business development companies, and utilities are structurally capital-intensive and are better judged on distributable cash flow, adjusted funds from operations, or regulated rate base than on plain FCF. The question itself does not change: is the distribution funded by recurring operations, or by something that has to be replenished?
When the payout lives on the liability side
The clearest warning label is a dividend that grows while net debt grows faster. This is not automatically a red flag — a company financing a value-accretive acquisition may lever up and raise the payout in the same year — but the pattern deserves scrutiny when capital spending is flat, revenue is decelerating, and the distribution still climbs.
Watch three lines together: total debt, interest expense, and dividends paid. If the dividend rises while interest coverage slides, the company is prioritizing the appearance of health over its substance. Management teams know a cut is punished immediately and severely. Markets forgive leverage far more readily than they forgive a broken payout, which is precisely why boards delay reductions — and why the delay is itself information.
The tell usually surfaces in the financing section of the cash flow statement before it surfaces anywhere else. A company issuing debt in a quarter when it also repurchased stock and paid a special dividend is not returning capital. It is rearranging it in a way that flatters per-share metrics.
Buybacks at peak multiples: the other half of the yield
Total shareholder yield — dividends plus net buybacks, divided by market capitalization — has become the standard framing, and it is useful as long as both components are read together. Repurchases create value when shares are bought below intrinsic value and destroy it when they are bought above. The mechanism is simple: buying back stock at a high multiple shrinks the share count but transfers wealth from continuing holders to selling holders.
The pattern to distrust is familiar. A stock trades at a cyclically elevated multiple, management authorizes a large program, and the buyback absorbs cash that could have funded the dividend or reduced debt. When the cycle turns, the share count is lower but so is the equity base — and the dividend that looked covered now needs the debt capacity the repurchase consumed. The company has effectively bought high and borrowed to do it.
Compare buyback dollars with the average price paid, disclosed quarterly, against the stock's long-run valuation range. A program executed at 30 times earnings in a business that historically traded at 15 is not a return of capital. It is a bet that the multiple persists. Sometimes it does. The point is that it is a bet, not a mechanical act of generosity.
Where the warning becomes a signal
A yield that outruns the business tends to widen before it breaks. As the payout ratio climbs past the comfort zone, the equity often falls faster than the dividend grows, pushing the quoted yield to levels that look like opportunity. Income screens surface the name. Yield-focused funds add it. Retail buyers arrive precisely when coverage is weakest, the opposite of what the arithmetic would recommend.
Three checks worth running before the next ex-date:
- Coverage trend, not level. A payout ratio rising for four consecutive quarters is a trend. The level alone is a snapshot.
- Financing activity in the same period. Debt issuance or asset sales alongside a steady dividend is a funding story, not an earnings story.
- Dividend growth versus capital spending growth. When capex is being deferred to protect the payout, the business is being harvested rather than run.
None of this argues against income investing. It argues against treating the distribution as a verdict. The dividend is a number the board chose, and boards choose under constraints retail holders rarely see until the constraint becomes binding.
The price of mistaking a yield for a verdict
The most expensive dividend is the one bought for the yield and held through the cut. By the time the reduction is announced, the equity has usually repriced, and the income investor has absorbed both the capital loss and the disappearance of the cash flow they were counting on.
Read the payout the way you would read any other financing decision: as a statement about what the business can afford. When cash flow covers it, the dividend is a return. When the balance sheet covers it, the dividend is a loan — and the lender eventually sends a bill.