Read the Footnotes Before They Read You: Five Balance Sheet Traps Sitting in Plain View
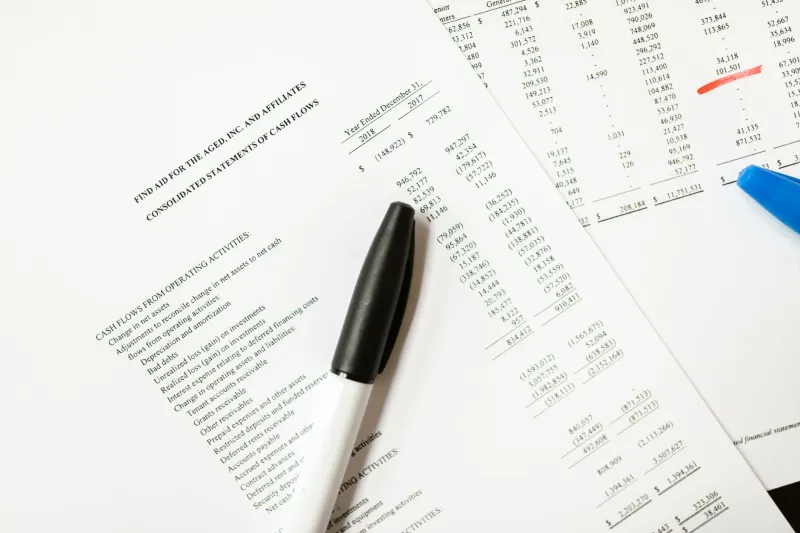
Most retail investors read a 10-K the way they read a movie trailer: revenue, EPS, maybe a glance at cash. Meanwhile, the most predictive disclosures in the document sit in footnotes numbered in the forties, written in deliberately soporific prose. The market's best short sellers read those pages first. Here are five of the landmines they're looking for — and how each one has shown up before a breakdown.
1. Deferred Revenue Games
Deferred revenue — cash collected before it's earned — is normally a strength. It becomes a warning when the trend reverses while headline growth holds.
The tell: revenue keeps climbing while the deferred revenue balance shrinks. That means the company is increasingly recognizing backlog rather than booking new business. SaaS companies that pulled forward multi-year contracts to prop up growth numbers frequently showed this divergence two to four quarters before decelerating billings made it obvious. Check the revenue recognition footnote and compute deferred revenue as a percentage of trailing revenue, quarter over quarter.
2. Off-Balance-Sheet Commitments
The commitments and contingencies footnote is where leverage goes to hide. Purchase obligations, take-or-pay supply contracts, guarantees, and unfunded capital commitments are all future cash claims that never appear as debt on the balance sheet.
A retailer signing ten-year lease guarantees, or a manufacturer guaranteeing a supplier's financing, can carry debt-like obligations that only surface when the counterparty fails. When a company's disclosed commitments exceed its cash and expected annual free cash flow combined, the "net debt" figure in the investor deck is fiction. Read Note 1's accounting policies and the dedicated commitments note in full — every quarter.
3. The Pension Gap
For legacy industrial and airline companies, the pension footnote is a landmine with a long fuse. The critical number is the funded status: the gap between plan obligations and plan assets.
The subtle warning appears in the assumptions. A discount rate assumption that drifts upward while peers hold steady artificially shrinks the reported liability. A expected return on plan assets set at 8% in a low-rate world means the pension income boosting earnings is an accounting construct, not cash. Companies have spent decades smoothing these gaps across generations of shareholders — and the bill eventually arrives, usually in the form of mandatory contributions during a downturn, when cash is scarcest.
4. Covenant Fine Print
The debt footnote discloses more than interest rates. It discloses how much room management has before lenders take control.
Look for leverage ratio covenants, minimum EBITDA tests, and — most telling — recent amendments or waivers. A company that renegotiated covenants mid-year is a company that nearly breached them. Also note restricted payment provisions: if the covenant blocks dividends, buybacks, or acquisitions without lender consent, management's stated capital return plans are contingent on fine print most shareholders never read. The filing flags these as "subsequent events" or amended credit agreement exhibits. They are rarely accidental.
5. Receivables Aging
Revenue can be massaged; cash collection is much harder to fake. The receivables footnote — often combined with an allowance for doubtful accounts — reveals whether reported sales are turning into money.
The red flag pattern: accounts receivable growing faster than revenue, days sales outstanding creeping upward across several quarters, and an allowance for doubtful accounts that declines even as older receivables pile up. This combination has preceded restatements and revenue recognition scandals at companies where aggressive channel stuffing — shipping product distributors can't actually sell — was quietly inflating the top line. When customers are paying slower every quarter, the income statement is describing a business that exists mainly on paper.
Building the Habit
None of these five items requires an accounting degree — only a routine. Twenty minutes per 10-K, focused on the notes rather than the narrative, will put you ahead of the overwhelming majority of retail holders of any given stock.
The consistent pattern across all five landmines: the disclosure was legally complete, publicly available, and ignored. Stocks rarely break down without warning. The warnings are simply filed in the part of the document nobody reads.